
Thailand Proposed 1,000 Baht Departure Tax 2026 Consultation
Based upon a recent article in The Nation newspaper Thailand’s Ministry of Finance and Revenue Department have opened a 30-day public consultation on draft legislation titled the Departure Tax Act, w/ submissions accepted until Oct 29, 2026. The consultation, conducted through the Thai Government’s central legal consultation portal https://law.go.th/ seeks stakeholder inputs, opinions and feedback before the proposal proceeds through the more formalized legislative process. Its however important to note that the proposed measure remains an unapproved legislative draft at the time of writing this article. No formal Departure Tax is currently being collected, and the consultation does not establish a formal commencement date as it’s simply at the consultation phase at the moment. Should this Departure Tax Act be enacted, the proposed legislation would take effect within 180-days of first being published within the Royal Gazette.
Core Structural Provisions
(1) Universal Applicability
Unlike Thailand’s previous departure tax framework, first introduced back in 1983 and originally focused on Thai nationals and foreign nationals authorized to reside in Thailand, the proposed legislation would be all encompassing and apply universally to travelers of all nationalities. Under the proposed draft, every qualifying passenger departing Thailand by air would be liable for the tax, regardless of nationality, visa category or residency status.
(2) Stage-by-Stage Rollout
Applied first to outbound commercial flights, while land and maritime departures remain temporarily excempt.
(3) Financial Parameters
The proposed initial rate for outbound air travel is 1,000 THB (One Thousand Thai Baht) per departure, allowing the applicable rate to be adjusted within that ceiling through subordinative legislation without requiring any new primary Act of Parliament. Whilst a figure of 5,000 THB (Five Thousand Thai Baht) is the maximum statutory ceiling and is not (I repeat not) the proposed initial charge at least not at the time of writing this article.
(4) Automated Ticketing Collection
In order to streamline and fast track the entire process, the proposed system is designed to operate through existing airline and ticketing systems, w/ the Departure Tax being already incorporated into the passengers airfare at the time of booking. Travelers would therefore not be required to make a separate payment at the airport or undergo any additional processing delays at the point of departure.
Exemption Thresholds
The Revenue Department intends to align the proposed exemptions broadly w/ existing Passenger Service Charge exemptions. The proposed Departure Tax Act draft provides exemptions for the following categories of passengers such as:
(a) Diplomatic & Sovereign Delegations i.e. Members of the Royal Family, Official Guests of the Crown or Thai Government, Foreign Heads of State, along w/ fully Accredited Diplomatic Representatives.
(b) Transit Passengers i.e Passengers traveling on international transit arrangements who importantly must remain within the designated airport transit areas, along w/ qualifying Domestic Transfer Passengers who remain airside.
(c) Infants & Operating Staff i.e. Children aged under 2 Years old or under, together w/ Active Aircrew traveling in the course of their duties without purchasing a commercial passenger ticket.
(D) Specialized Missions i.e. Official State Aircraft Personnel and Qualifying International Inspection and/or Official Mission Personnel.
Macroeconomic Rationale vs. Private-Sector Interests & Concerns
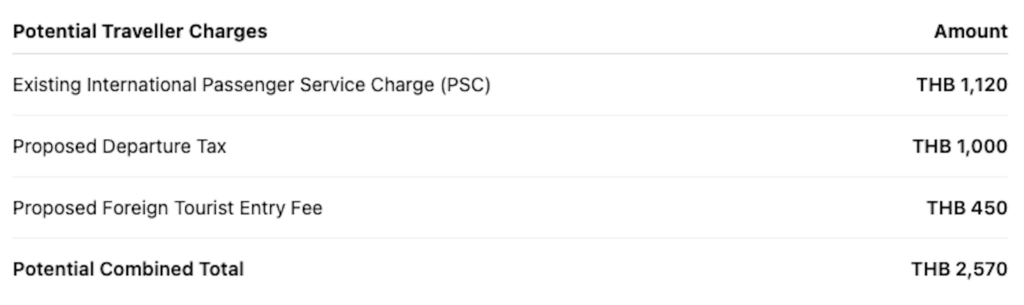
The Potential Combined Total is at present simply a potential combined figure, rather than a current charge. It assumes that all 3 measures apply to the same foreign traveler and that the proposed Tourist Entry Fee of 450 THB (Four Hundred & Fifty Thai Baht) is also introduced. At present, the only existing charge currently in operation is the International Passenger Service charge of 1,120 THB (One Thousand One Hundred & Twenty Thai Baht).
Government Rationale
The Thai Finance Ministry has purportedly cited 2 fundamental objectives for the proposed Departure Tax. First, the Thai Government, wishes to encourage Thai citizens to spend their tourism monies locally by holidaying domestically, thus boosting tourism expenditure within Thailand itself and supporting local economies. Second, its hoped that the proposed Departure Tax will provide the Thai Government w/ an additional fiscal mechanism to generate tax revenues that can be used to respond to future economic or other national emergencies (if any).
Obvious Industry Stakeholder Concerns
The Association of Thai Travel Agents (A.T.T.A.) has raised concerns about the cumulative effect of additional travel-related charges. Earlier in October 2026, A.T.T.A. representatives argued that combining the proposed Departure Tax of 1,000THB (One Thousand Thai Baht) w/ the existing International Passenger Service Charge (PSG) as well as the proposed Tourist Entry Fee of 450 THB (Four Hundred & Fifty Thai Baht) could potentially bring the combined cost up to 2,570 THB (Two Thousand Five Hundred & Seventy Thai Baht) per traveler. The Association of Thai Travel Agents warned that the accumulation of separate charges could increase the cost of visiting Thailand and place additional strain on the tourism sector at a time when the industry is already facing economic challenges which is further compounded by the rising costs of fuel.
Enforcement & Statutory Transition
(a) Grandfathering Protection
Under the proposed Departure Tax draft, any air tickets purchase and issued before to the proposed law’s effective date would be exempt, even if the actual journey takes place after the proposed legislation were to come into official effect.
(b) Collection, Audit & Penalties
The proposed Departure Tax draft provides the Thai Revenue Department w/ powers to assess and collect unpaid amounts and establish non-compliance penalties. Transport operators responsible for collecting and remitting the tax, could face a penalty equivalent to 2 times the outstanding tax, together w/ a 1.5% (One Point Five Percent) Monthly Surcharge on any unpaid amounts. The proposed Departure Tax draft legislation also includes enforcement mechanisms related to tax evasion, obstruction of officials and failure to comply w/ any statutory obligations.
Key Takeaway
The proposed Departure Tax Act represents a significant expansion of Thailand’s departure-tax framework because its universal and applies to travelers of every nationality. The measure remains under public consultation until October 29, 2026, after which it would still need to proceed through the legislative process inclusive of being published within the Government Gazette.
As for International travelers entering Thailand by air, the principal issue is not simply the proposed 1,000 THB (One Thousand Thai Baht) in isolation, but the potential accumulation of separate travel-related fees which may be the proverbial straw that breaks the camels back, especially in light of rising fuel prices as a direct result of the existing Strait of Hormuz crisis. In summary, the final scope, rate, exemptions and future implementation arrangement remain subject to the outcome of stakeholder consultation and the subsequent legislative process.
Last Updated October 08, 2026

